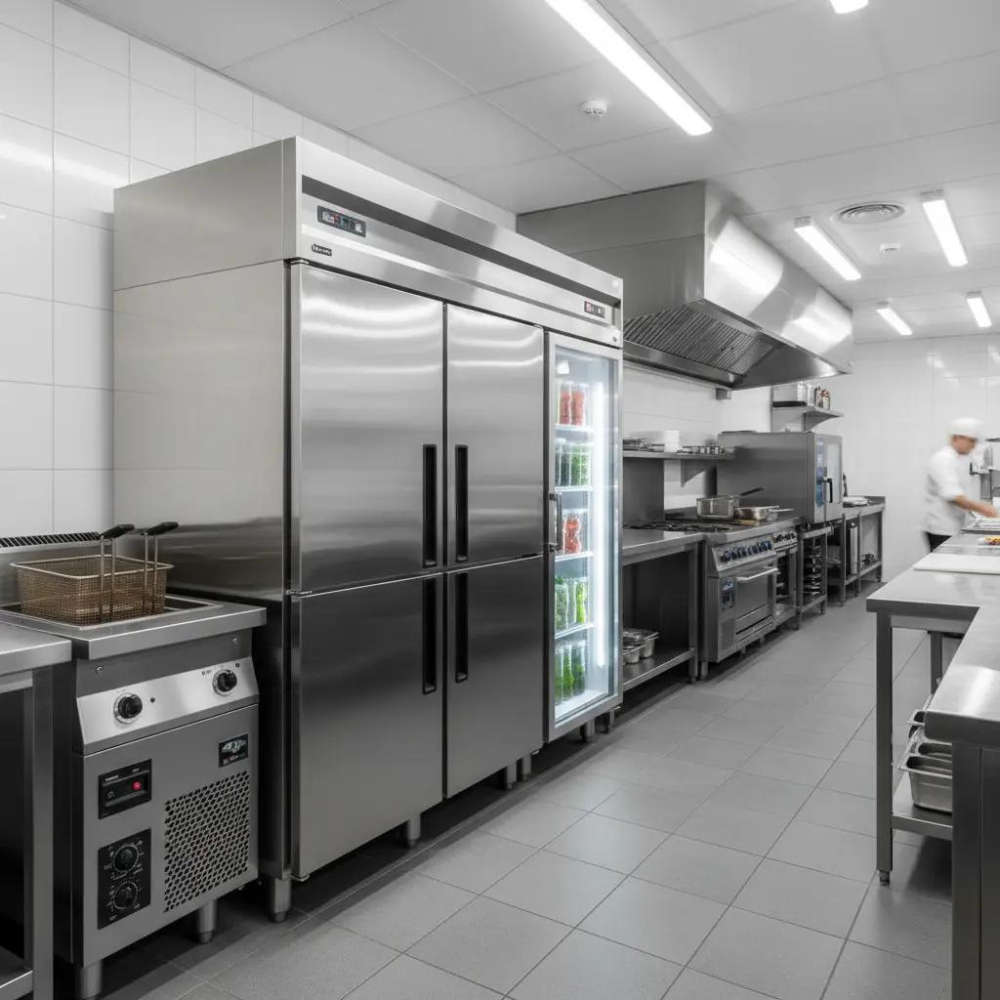
A refrigerator, freezer, or air conditioning failure can lead to costly repairs and spoiled inventory. Equipment Breakdown & Spoilage coverage can help cover sudden internal mechanical or electrical failures and the products lost as a result. Unlike Commercial Property Insurance, which covers external events such as fires or storms, this protection focuses on failures within the equipment. Omega Insurance compares carriers to find coverage that fits your operation and budget. A refrigerator, freezer, or air conditioning failure can lead to costly repairs and spoiled inventory. Equipment Breakdown & Spoilage coverage can help cover sudden internal mechanical or electrical failures and the products lost as a result. Unlike Commercial Property Insurance, which covers external events such as fires or storms, this protection focuses on failures within the equipment. Omega Insurance compares carriers to find coverage that fits your operation and budget.
Covers the repair or replacement of equipment that fails suddenly from internal causes such as mechanical failures, electrical issues, power surges, or motor burnout.
Replaces inventory that spoils when a refrigerator or freezer stops working because of a covered breakdown, including food and other perishable stock.
Protects refrigerators, freezers, A/C and heating systems, compressors, boilers, computer equipment, and electrical panels.
Depending on the policy, it can cover the income you lose while you repair the equipment and get back to normal operations.
It can cover additional costs to speed up repairs or rent temporary equipment, helping you cut downtime.
By covering both the equipment and the inventory, it keeps a single breakdown from turning into a major loss that hurts your finances.
If your business depends on equipment to operate, such as refrigeration, cooking, climate control, or electrical systems, a sudden breakdown can stop your operation and damage your inventory within hours. Many owners find out too late that their Commercial Property Insurance covers fires or storms but not the equipment’s internal failures or the refrigerated product that spoils because of them. Restaurants, grocery stores, butcher shops, produce markets, food trucks, and any business with a cold chain are the most exposed. At Omega, we explain your options, compare carriers, and help you find coverage that aligns with your operation, your risks, and your budget.


 Trustindex verifica que la fuente original de la reseña sea Google.

 Trustindex verifica que la fuente original de la reseña sea Google.
 Trustindex verifica que la fuente original de la reseña sea Google.
 Trustindex verifica que la fuente original de la reseña sea Google.
 Trustindex verifica que la fuente original de la reseña sea Google.
 Trustindex verifica que la fuente original de la reseña sea Google.
 Trustindex verifica que la fuente original de la reseña sea Google.
 Trustindex verifica que la fuente original de la reseña sea Google.
 Trustindex verifica que la fuente original de la reseña sea Google.
We help you find coverage that protects your equipment and the inventory that depends on it when a breakdown happens. Our team reviews options across trusted carriers to find protection that fits your type of business, your equipment, and your budget.
It is a commercial coverage that protects your business when a piece of equipment fails suddenly from an internal mechanical or electrical problem. It covers the repair of the equipment and the refrigerated or frozen goods that spoil because of that failure. It is usually added to your business policy or purchased as separate coverage.
Tools and Equipment Insurance covers theft or external physical damage to your tools and work equipment. This coverage is different because it responds to the equipment’s internal failures, such as when it stops working from a mechanical or electrical problem of its own, and to the loss of perishable inventory that failure can cause. They are different risks, and many businesses need both. At Omega, we help you see what truly fits you.
Usually, no. Commercial Property Insurance is built for external causes, such as a fire, a theft, or a storm, and it normally excludes internal mechanical breakdowns and electrical failures. That is why this coverage is added separately. In fact, many businesses need all three: Commercial Property, Equipment Breakdown, and Spoilage. At Omega, we explain what each one covers so there are no gaps.
It depends on the cause and the terms of the policy. Spoilage is usually covered when the loss comes from a covered equipment breakdown; some policies also include power service interruptions, sometimes with conditions such as a minimum outage length. At Omega, we review each carrier’s terms so you know exactly what is included.
The cost depends on the type and value of your equipment, the value of your inventory, your industry, and your coverage limits. It tends to be affordable compared to replacing a piece of equipment and your entire inventory out of pocket. As an independent agency, Omega compares options to fit your budget.